Mortgage Planning in Vancouver: Start Before You Shop
Vancouver is known for its distinctive combination of urban living, waterfront neighbourhoods and spectacular mountain views. For many buyers, purchasing a home here represents one of the largest financial commitments they will make.
That makes mortgage planning an essential part of the home-buying process.
Instead of starting with the question, “How much house can I buy?”, prospective buyers may find it more useful to begin with:
“What monthly housing cost fits comfortably within my financial situation?”
A mortgage isn't simply the purchase price minus your down payment. Buyers also need to consider interest, property taxes, insurance, maintenance, closing costs and other expenses associated with owning a home.
1. Get Mortgage Pre-Approval Before You Start House Hunting
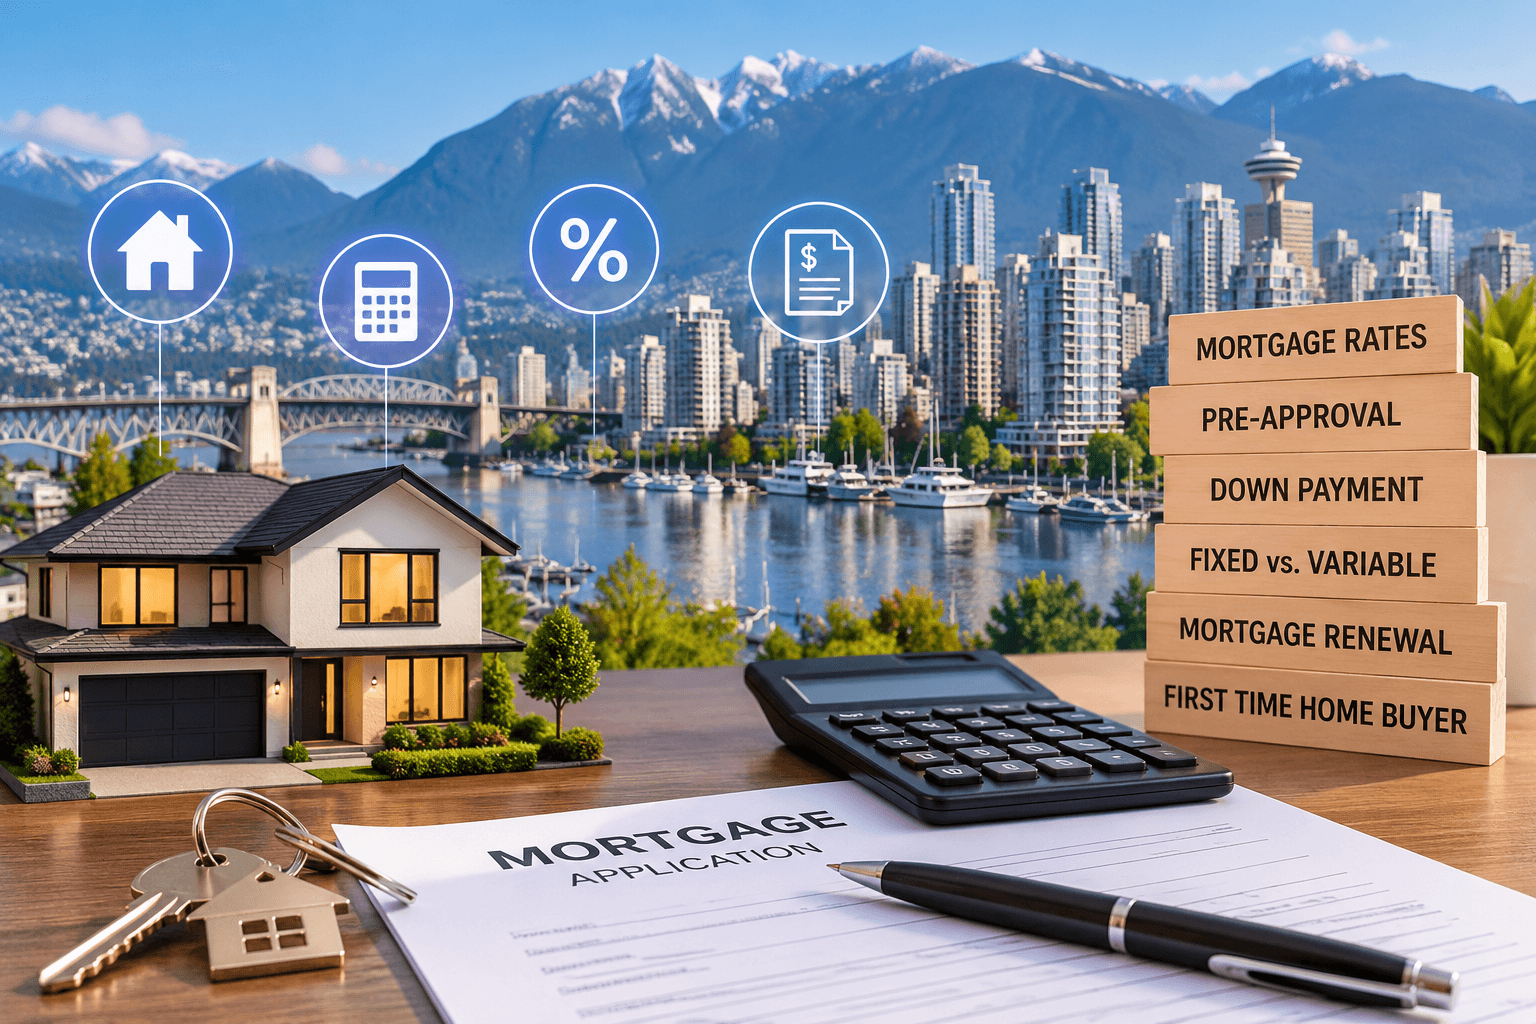
The mortgage pre-approval shown in the image is one of the most important early steps for prospective Vancouver buyers.
A lender or mortgage broker generally reviews factors such as your income, assets, debts and down-payment funds. A pre-approval can help estimate how much you may qualify to borrow and may allow you to lock in an interest rate for a specified period, depending on the lender. However, pre-approval is not a guarantee of final mortgage approval. Canada
For Vancouver buyers, knowing your approximate financing capacity before making an offer can make the search more focused.
It's also important not to automatically treat the lender's maximum approval as your personal budget.
A lender may tell you that you qualify for a particular mortgage amount, but you still need to consider whether the resulting payment leaves enough room in your budget for:
Property taxes
Home insurance
Strata fees, where applicable
Utilities
Repairs and maintenance
Emergency savings
Transportation
Family expenses
Future financial goals
Being approved for a mortgage and being comfortable with a mortgage are two different things.
2. Understand Your Down Payment
The calculator and house keys in the image also represent another major part of Vancouver home buying: the down payment.
Under current federal guidance, the minimum down payment depends on the home's purchase price. For homes priced at $500,000 or less, the minimum is generally 5%. For homes between $500,000 and $1.5 million, the minimum is 5% on the first $500,000 and 10% on the portion above $500,000. At $1.5 million or more, the minimum down payment is generally 20%. Canada
Buyers putting less than 20% down will typically need mortgage loan insurance, subject to applicable rules. Canada Mortgage and Housing Corporation
Why does the down payment matter?
A larger down payment can reduce the amount you need to borrow and can therefore reduce interest costs over the life of the mortgage.
For example, consider a hypothetical $1 million home:
5% down: $50,000
10% down: $100,000
20% down: $200,000
The actual financing requirements, insurance eligibility and costs depend on the property, borrower and applicable lending rules, so buyers should confirm their situation with a lender or mortgage professional.
3. Fixed vs. Variable Mortgage Rates
The “FIXED vs. VARIABLE” sign in the image reflects one of the biggest decisions borrowers face.
Fixed-rate mortgage
With a fixed mortgage, the interest rate remains the same during the mortgage term. This can make payments more predictable and easier to budget. Canada
For buyers who value payment predictability, this structure can make household budgeting easier.
Variable-rate mortgage
A variable-rate mortgage can change as interest rates change. Depending on the mortgage structure, a change in rates can affect either the amount of the payment, how much of the payment goes toward interest, or both. Canada
This means buyers should look beyond the initial advertised rate.
Instead, ask:
How would my payment change if rates increased?
How much principal would I pay down?
What happens if rates fall?
Are there restrictions on switching or refinancing?
What are the penalties for breaking the mortgage?
Is the mortgage portable?
What are the prepayment privileges?
The lowest advertised rate isn't necessarily the only factor that matters.
4. Mortgage Term vs. Amortization
These two terms are sometimes confused.
Your mortgage term is the period during which your mortgage contract is in effect. Canadian mortgage terms can range from several months to five years or longer.
Your amortization period is the overall length of time it would take to repay the mortgage if payments and other conditions remained consistent.
A longer amortization can reduce the size of individual payments, but it generally means paying interest over a longer period. Canada
For Vancouver homeowners dealing with substantial property values, understanding this distinction can be particularly important when comparing mortgage options.
5. Don't Forget Mortgage Renewal
The wooden blocks in the image include “MORTGAGE RENEWAL”, and this is an important part of Canadian homeownership.
Your mortgage doesn't necessarily disappear after the first few years.
At the end of your mortgage term, you normally need to either pay the outstanding balance in full or renew the mortgage. Many homeowners go through several mortgage terms before the mortgage is completely paid off. Canada
Mortgage renewal is therefore another opportunity to review your financial situation.
Before renewing, consider:
Your current mortgage balance
Your new interest rate
Your remaining amortization
Whether your income has changed
Whether you want to increase payments
Whether another lender offers different terms
Whether you plan to move
Whether refinancing makes sense
For federally regulated financial institutions, lenders must provide certain renewal information at least 21 days before the end of the existing term. Canada
Don't automatically assume that renewing with your existing lender is your only option.
6. First-Time Home Buyers in British Columbia
The image also highlights “FIRST TIME HOME BUYER,” which is particularly relevant for Vancouver-area buyers.
British Columbia's current First Time Home Buyers' Program provides a property transfer tax exemption for qualifying buyers. For properties registered on or after April 1, 2024, eligible buyers can receive an exemption on the first $500,000 of the property's fair market value when the property is valued at $835,000 or less. A partial exemption may apply for qualifying properties above $835,000 and below $860,000. Government of British Columbia
Eligibility requirements apply. Among other conditions, the program generally requires the buyer to be a Canadian citizen or permanent resident, meet B.C. residency or tax-filing requirements, and not have previously owned a registered interest in a property that was their principal residence. Government of British Columbia
For someone purchasing their first Vancouver-area home, understanding these programs before making an offer can be an important part of budgeting.
7. Look Beyond the Mortgage Payment
One of the biggest mistakes first-time buyers can make is focusing exclusively on the mortgage payment.
Homeownership comes with additional expenses.
Depending on the property, buyers may need to budget for:
Property taxes
Annual municipal property taxes can add a significant amount to the cost of ownership.
Strata fees
Condo and townhouse owners may have monthly strata fees and potential special assessments.
Home insurance
Insurance costs vary depending on the property and coverage.
Maintenance and repairs
Roofs, appliances, plumbing, heating systems and other components eventually require maintenance or replacement.
Closing costs
Legal fees, inspections, adjustments and applicable taxes should be considered before purchasing.
Emergency savings
Owning a home without an emergency fund can create financial pressure when unexpected repairs appear.
The goal isn't simply to qualify for the purchase.
The goal is to build a housing budget that remains manageable after you receive the keys.
A Practical Vancouver Mortgage Planning Checklist
Before making an offer on a Vancouver property, consider working through this checklist:
Financial preparation
☐ Review your income and monthly expenses
☐ Check your credit profile
☐ Determine your available down payment
☐ Keep funds available for closing costs
☐ Establish an emergency reserve
Mortgage preparation
☐ Compare lenders or mortgage brokers
☐ Obtain a mortgage pre-approval
☐ Understand the interest rate and mortgage term
☐ Compare fixed and variable options
☐ Understand prepayment privileges
☐ Review penalties for breaking the mortgage
☐ Understand renewal and refinancing options
Property preparation
☐ Determine your realistic purchase budget
☐ Review property taxes
☐ Check strata fees where applicable
☐ Review the property's condition
☐ Consider future maintenance costs
☐ Understand the neighbourhood and transportation options
First-time buyers
☐ Check whether you qualify for B.C.'s First Time Home Buyers' Program
☐ Research applicable federal home-buying programs
☐ Confirm eligibility before relying on a tax exemption
Vancouver Homeownership Requires a Long-Term Plan
The Vancouver skyline shown in the image represents more than beautiful scenery. Behind every home purchase is a financial decision that can affect a household for many years.
Mortgage rates can change. Income can change. Property expenses can increase. Mortgage terms eventually expire and need to be renewed.
That's why a thoughtful home-buying strategy should consider not only today's mortgage payment, but also what your finances could look like several years from now.
For Vancouver buyers, the process can be simplified into a few fundamental steps:
Know your budget → Get pre-approved → Understand your down payment → Compare mortgage structures → Calculate the total cost of ownership → Plan for renewal → Then choose the property.
A home should fit into your financial plan—not the other way around.
This article is for general educational purposes and is not mortgage, legal, tax or financial advice. Mortgage rules, rates and government programs can change. Buyers should confirm current requirements with their lender, mortgage broker, lawyer/notary and the applicable government agencies.